S | M | S

admin

Tips for Taming Work Comp Subpoenas

Tips for Taming Work Comp Subpoenas Legal copy services are a fact of life in the legal world. No attorney practicing today can live without them, unless we could dedicate our whole day to the minutiae of document preparation and dissemination. They are an essential service that we rely on. But let’s face it. They run a business and will always try to bolster their bottom line.  Since there are strict rules as to which party pays for legal copy services and when, the ledgers get a little muddy. Lawmakers have stepped in to try and streamline the industry, but there are always ways to figure out how to sidestep regulations.  Following, I’ve prepared a list of the current tricks employed by copy services and how you can spot them, outmaneuver them, and prevent getting gouged.   But first, a little background. A number of years ago, I drafted a two-part article series about the perils of copy services and their subpoena and billing practices and how to mount a successful defense against them. It resulted in one well-known provider in Northern California writing a “white paper” in response to my article, which was filled with some small counter arguments and not much more. In the years subsequent to those articles, a lot has changed in the world of copy services and their practices. The most notable change was the passage in 2012 of California SB 863. SB 863 and its impact on subpoenas SB 863 implemented a fee schedule for copy services. This ended, for the most part, the “wild west” of service fees. In my opinion, SB863 and the implementation of a copy service fee schedule was implemented at least in part, to prevent unnecessary copy service charges that typically occur throughout the life of the claim. Signed in August of 2012 and later codified in Labor Code §5307.9, SB 863 ultimately resulted in a fee schedule that went into effect on 7/1/15 (see also 8 CCR §9980-9983 for more information).  The fee schedule did a number of things:  Placed a flat fee on copy costs for pages below 500 Added a per page cost above 500 pages Cancelled other subpoena costs Created flat fees for records from certain agencies Gone were the days of $300+ bills for a Certificate of No Records. Useless charges for “base rate”, phone calls, mileage, pagination, bates stamping were ghosts of billing abuses past. And the defense side rejoiced. But not me! I chose to operate on the assumption that like other billing phenomena in the Workers’ Compensation world such as positional MRI’s and re-packaged and compound medications, providers would simply find another way to recoup that lost income. I was right.  I’ve compiled a list of tricks I have noticed that copy services are pulling in light of SB 863, which in all seriousness really was a hit to their bottom line.  Read: Is the claim contested? Trick #1- Subpoenas issued immediately upon representation  SB 863, codified by 8 CCR §9982(d)(1) established a waiting period of 30 days for the defendant to provide records upon request and also discusses “allowable services”.  In the event the applicant’s attorney sends a letter of representation and makes a request for records from the defendant, the defendant is not liable for charges associated with records provided during this waiting period by the carrier, claims administrator, or party that is not a professional photocopier.  The first “trick” I wish to address is the subpoena immediately upon filing of an Application of Adjudication or simply when applicant’s attorney sends their boilerplate introduction letter and makes a general request for records. I have been told on more than one occasion that it is commonplace for most of the larger copy service companies to have a de facto “desk” at many applicant attorney’s offices, where they come by multiple times a week to inquire about new claims to be filed and immediately proceed with multiple subpoenas to parties such as employer, carrier, known physicians, private treating physicians and others.  I would argue that contrary to many copy service providers’ claim that a subpoena issued by them starts this 30 day clock, the Code does not specify this. Further, this would defeat the purpose of the fee schedule. If a subpoena is issued during this timeframe and the defendant provides the records to applicant’s attorney directly, can the copy service cancel their subpoena and hit you with a $75.00 charge?  I would argue no! By issuing immediate subpoenas, they anticipate that:  The defendant will not comply with a 30-day requirement Parties served with their subpoenas will automatically comply, thus “justifying” their billing and  They can establish a pattern of additional subpoenas, which we will discuss below.   Trick #2- Ongoing/updated subpoenas Any defense attorney or claims examiner who has worked for longer than a week at an active desk has experienced this. New applicant’s attorney? Here’s your subpoena. New primary treating physician? Here’s your subpoena. The defendant issues a subpoena for a particular location? Here’s a subpoena for the same location. Ongoing medical care? Here’s your updated subpoena.  The most common arguments that I hear are four-fold.   The first argument I usually hear is that the original request for records in the boilerplate form sent by applicant’s attorney at the start of the claim creates an ongoing requirement for a file and serve. I concede that this argument may have some merit, yet we must jump into the weeds to dissect it. With an ongoing duty, I am not aware of a set “required time” to comply with ongoing file and serves. I recommend every 45 days the claims examiner provide updated reports and upon the receipt of a DOR. However, I always argue upon receipt of an updated subpoena for ANY location in which the defendant has records, that we treat that subpoena as a request for records from the applicant and comply with the request within 30 days.   I always make it a point to demonstrate to the WCAB that

Tips for Taming Work Comp Subpoenas Read More »
How L.A. traffic changed deposition procedure

How L.A. traffic changed deposition procedure A few days ago, I was in a very normal, run-of-the-mill deposition in Los Angeles. Once the opposing counsel had finished squeezing blood out of the rock that was my witness (“Where did you go to preschool?”), I recited the usual deposition-ending stip: “I stipulate that we relieve the court reporter of her duties under the California Code of Civil Procedure and allow the original transcript of this deposition to be sent directly to the witness or witness’ attorney for reading and signature.” As usual, all counsel around the table stipulated. As we started to close up shop, thus beginning the shuffling ritual of getting the hell out of there, the court reporter suddenly got a gleam in her eye. She reached into her briefcase and plopped a document on the table in an action that can only be compared to Julia Roberts walking out of Gucci with several shopping bags shouting “Big mistake! Big!” I picked up the document and gave it a lawyerly glance, and acting like I knew exactly what it was all about, said ‘What’s this all about?” Could it be true? The SoCal Stip was dead! Where did the SoCal Stip come from to begin with? By statute, the court reporter has to retain custody of the original transcript. Back in the day, before computers and Candy Crush, witnesses would have to physically drive, bus or gallop to the court reporter’s office to review the original transcript, make changes and approve it. This process worked just fine until L.A. became the place to be and people started choking the freeways and making getting just about anywhere generally impossible. So, in the 70’s, SoCal lawyers started to realize it was getting ridiculous for witnesses to have to commute for an hour to read their own words. More importantly, witnesses started to realize this as well and stopped showing up. This resulted in a major backlog, missed deadlines and headaches for all. Little by little, lawyers started to introduce this stipulation, the SoCal stip, in order to put themselves in control of managing changes with the witness. It saved a lot of time and a little bit of money. I often have depositions in Northern California and this stipulation is never used there (is traffic is lighter in San Francisco?). Going from North to South, lawyers start using it around Santa Barbara. 40 years later, apparently, we can send certified original transcripts to witnesses in a nanosecond thanks to the internet and computers. And, unless you’re on dialup, there’s no traffic. Court reporters have to follow the law, too! You’ve really got to like typing. It takes about two years to get a degree in court reporting and then there are several certifications and tests. As you progress in your career, you acquire all kinds of skills that allow you to report in progressively more lucrative situations. It’s a great job and worth defending. One of the main things court reporters have to do is, surprising to some, follow the law. If they don’t, they get stripped of their certifications. It makes sense that court reporters would be very hesitant to agree to any stipulation that violates the law. Turns out that every time SoCal lawyers used the SoCal Stip, they were stipulating that the court reporter break the law! The SoCal stip is illegal (since Nov 1) You can understand why witnesses, counsel and reporters, formed a gentleman’s agreement: THE TRAFFIC IS REALLY TERRIBLE IN L.A., GUYS! But, times have changed – thus the gleam in our court reporter’s eye that day. The document in my hand was the SoCal stip’s death certificate. It’s over. Thanks Al Gore… and Steve Jobs. Want to hear this riveting story in person? Give me a call – I’m happy to discuss this or any California subrogation issues you have. ccapalbo@siegelmoreno.com – 619-525-7626 Search for: Search Categories COVID-19 Depositions Firm Announcements Firm Notifications Giving Back Law New Attorneys New Location Property Subrogation Subrogation Workers' Compenstation Archives Archives Select Month August 2026 March 2026 January 2026 July 2025 May 2025 March 2025 January 2025 November 2024 October 2024 July 2024 June 2024 January 2024 December 2023 November 2023 August 2023 May 2023 April 2023 March 2023 February 2023 May 2022 March 2022 February 2022 January 2022 November 2021 October 2020 September 2020 August 2020 June 2020 May 2020 April 2020 March 2020 January 2020 November 2019 October 2019 September 2019 March 2019 February 2019 January 2019 August 2017 January 202 Subscribe To Our Blog First Name Last Name Email * Edit Template

How L.A. traffic changed deposition procedure Read More »

How to prevent your California property subrogation case from getting too hot

How to prevent your California property subrogation case from getting too hot When I’m not in court, I often spend a majority of my day as a California subrogation attorney in my office peering over stacks of paper – pleadings, discovery, motions, medical records (you get the idea). On some of my favorite days on the job, though, you’ll find me in a hard hat and my trusty steel-toed boots sifting through an accident scene trying to figure out what exactly happened to the site, and why. This is when I’m in what I love to call my “Veronica Mars” mode. I get to put on my investigating attorney hat and sift through the aftermath of a property loss – looking for clues to help me prove what happened, and who is to blame. I happen to handle a lot of property loss cases involving fires that originate from the malfunction of an ordinary household product. Several of these have been the result of a microwave failure – they’re more common than you think – or are probably comfortable thinking about. When I get that call involving a property fire, the first thing I do is ensure the scene is secure and preserved, and then I grab my investigator gear and get to the scene as quickly as I can. Preserving  the scene Securing the scene and timing are essential in these situations. This is because any change in the scene can destroy your evidence. Trust me. Don’t let it happen to you. There will be a lot of well meaning people trying to get in to the property to do their jobs as quickly as possible. While this is great, and these people are appreciated, they can inadvertently annihilate any chance you have at subrogation recovery without meaning to. When you control the scene, you control your recovery potential. So many things can happen to a loss site if you’re not proactive in stabilizing and preserving the scene. If you always keep in mind the basic “who, what, why” questions, it can help you better evaluate the best course of action for the scene. This includes the need for estimation for repair, clean up, and liability investigation. You have to make sure you’re aware of who is at the scene, why and what they are doing. Keeping track of this in a quick notes section is also extremely helpful when arguing your subrogation case because you can use that information to show the scene was not altered. Preserving the scene also requires putting all potential liable parties on notice that they may be liable, and giving them the opportunity to inspect the scene themselves. This can be time consuming, and difficult when you are trying to mitigate damages and get all repairs completed as quickly as possible. If you don’t do this, however, those potentially liable parties will use your failure to provide them access to the scene before it is altered as evidence that the scene was not handled properly, and attempt to discredit your subrogation claim against them. Securing the failed product Most importantly, you have to get a hold of that microwave. Physically be in possession of the evidence and your subrogation recovery potential increases exponentially. As the property insurance carrier, our subrogation rights come from standing in the shoes of our insured. In these types of cases our insured is usually the owner of the property. When that is the case, it is a simple task of talking to the insured and our investigators to make sure the product is secured and taken into custody to be stored as evidence. This also makes the product easily available for further inspection and testing later on. If the insured isn’t the owner of the product, obtaining control of the product is more difficult, but can be done with some quick work and investigation into who owns the product. A case study Let’s look at a recent property case involving a microwave I was involved in, and how good old-fashioned investigation helped my client recoup 95% of their total damages. The case involved a fire that started with a microwave in a large two story building. The event caused extensive fire damage, and the bottom floor had to be fully restored. The cause and origin of the damage clearly pointed to the area of the microwave, and since I’ve seen this exact scenario before, I moved to get control of the microwave right away. It was very clear to my expert and cause and origin investigators that the fire must have originated with the microwave. Finding out what caused the microwave to malfunction, however, was a different hurdle to get over. I had my inspector inspect the subject microwave, and we acquired an exemplar unit to compare a new model with the damaged one. We took the damaged microwave apart piece by piece inspecting, xraying and documenting the state of that piece compared to the same piece in the exemplar machine – it took us an entire day. Just when we thought we wouldn’t be able to find the exact issue that caused the malfunction and ultimately the fire: voila! We found a piece in the subject microwave that looked odd, a piece that did not match the exemplar and didn’t fit the specifications outlined in the microwave’s manual. In some cases of microwave failure, the issue stems from a rotator defect in the motor controlling the movement of the fan belt. When power is connected to the unit, and the product is faulty, that motor can “tell” the fan belt to run and run, never fully catching and running properly, until it finally overheats and catches fire. That’s exactly what happened in this case. So, we sued the usual suspects for a product liability case: the designer, manufacturer and the supplier of the product – essentially anyone that benefited from the sale of the microwave. They were put on notice that we believed their product was

How to prevent your California property subrogation case from getting too hot Read More »

Governor Newsom signs new bills – Will they affect you?

Governor Newsom signs new bills – Will they affect you? Governor Gavin Newsom closed out the 2019 California legislative session this week by signing a slew of bills into law. He’s signed over 800 this year and vetoed 170. That’s a lot of new laws. The laws, which go into effect on January 1, 2020, create new rules for things from gun purchases to roadkill. We want to look at the laws that have to do with our corner of the world: workers’ compensation. AB 1804 – Requires any serious workplace injury to be reported immediately to CalOSHA. Notification can be given by telephone or by an unseen (so far) online mechanism. We read a lot of OSHA reports and we do notice that there can be a reporting lag. This is often due to the general chaos at a workplace these situations can create. At other times, clear chains of command and/or management structure are not understood or in place. Most simply, people don’t know who is supposed to do it and when. The law will definitely help give us more insight into these types of injuries. Since reporting is done immediately, the incident is more fresh in the mind of the reporter and can help establish facts sooner. AB 1805 – Currently, to define and injury  or illness as “serious” for workers’ compensation purposes, the injured worker must have an immediate stay in a hospital for at least 24 hours. This is no longer the case. The new law lifts the minimum hospital stay time. This will lower medical costs for hospitalization, but it also might increase the the size of claims as more and more injuries will qualify for the “serious” designation. The law also changes the definition of “serious exposure” to a hazardous substance to include “a realistic possibility that death or serious physical harm in the future could result from the actual hazard created by the exposure.” We believe this to mean (we’ll see what the courts say) that no physical harm has to be immediately present in order to declare the event a “serious exposure.” SB 542 – Expands workers’ compensation payments for psychiatric injury, including PTSD, for first responders. Currently, “presumptions” (workplace injuries that, for the most part, first responders are expected to suffer from) include heart disease, cancer and hernias. Psychological injury now has a stronger presence on the list of these presumptions because now, the worker does not have to prove that the injury was at leas 50 percent related to their job. Look for a lot more claims for psychological presumptions. AB 5 – One of the most contested bills in 2019 – not just in the work comp world, but in all of the legislation that came out this year, targets the “gig economy.” The law says that if a worker provides an essential function of their employer’s business, they are an employee of that business. No longer will businesses be able to lump these workers into the independent contractor category. These employees will now be entitled to benefits, including workers’ compensation. This far-reaching bill is really aimed at big companies like Uber who have thousands of these independant contractors that (depending on your point of view) perform functions essential to the business i.e.: Uber needs drivers to exist. But the law will also effect the construction, trucking, janitorial service, nail salons, adult entertainment, commercial fishing and media industries. Large tech companies already pledged their time and money to fight this. We’re always keeping an eye on developments with laws that affect our clients. Need more information? Contact us, or Give us a call! 619-525-7626 Search for: Search Archives Archives Select Month October 2019 September 2019 March 2019 February 2019 January 2019 August 2017 Subscribe To Our Blog First Name Last Name Email * Edit Template

Governor Newsom signs new bills – Will they affect you? Read More »

SMS Plays Ball in Sacramento

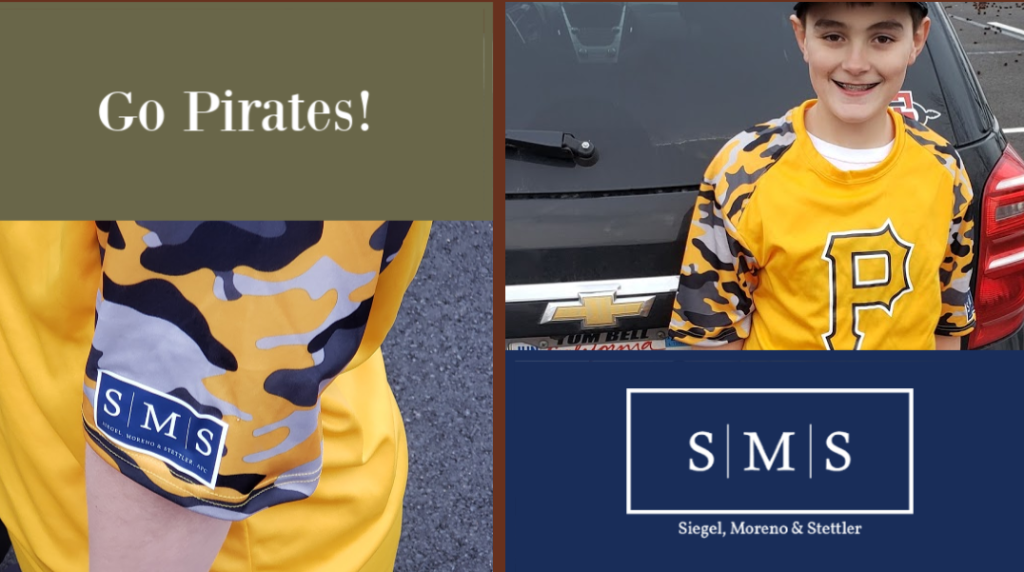
SMS Plays Ball in Sacramento We’re big baseball fans here at SMS. Our favorite team, of course, is the San Diego Padres because San Diego is where we started. But, we also have a favorite baseball team in Sacramento: The Rancho Cordova Little League Pirates. To show our support, we donated new practice jerseys and hats to the team this season. Because anything worth doing is made better when you look sharp. Says Sacramento workers’ compensation defense attorney Tim Rose (also the head of the SMS Sacramento office): “The jerseys arrived a few weeks ago and are the envy of the league. The team likes them better than their game jerseys and we have petitioned the league to allow for a few games to be played in them.” The athlete in the pictures is Ethan, the team’s starting first baseman and #3 slot hitter. The team also had three representatives at the district skills competition a few weeks ago and they all showed up in the jerseys and some of coaches were asking about them. Ethan and his teammate took first and second in the hitting skills competition! Here’s to a great season. Go Pirates! Search for: Search Archives Archives Select Month September 2019 March 2019 February 2019 January 2019 August 2017 Subscribe To Our Blog First Name Last Name Email * Edit Template

SMS Plays Ball in Sacramento Read More »

What you need to know about premises liability

What you need to know about premises liability The 21st century’s new “gig economy” has opened endless new opportunities for individuals to market and profit from their personal skills and assets. Firms like Uber, TaskRabbit, Airbnb*, to name a few, leverage emerging technology to connect customers to products and service providers on a microscale. This results in increased convenience for customers, lower prices and a share in what has become the future of commerce. But with these advances come questions about insurance coverage and liability. Here, we’ll look at Airbnb and discover what the company’s liabilities are when they broker short-term rentals between homeowners and guests. Consider this hypothetical: Your insured retails high-end pots and pans. Most of their business comes from large hotels and restaurant chains. Your insured has no brick-and-mortar store, per se, so most sales are done in the field. Employees of your ensured regularly travel to other cities to meet with buyers in person. Generally, these employees stay in national chain hotels. But recently, your insured has noticed that they can save considerable amounts on lodging expenses by housing multiple employees in Airbnbs at the same time. Your insured sends a group of employees to Palm Springs and books a three bedroom house they found on Airbnb. While in residence at the Airbnb, one of the employees (we’ll call her Belinda) slips on loose, improperly secured tile in the bathroom and suffers serious injuries. Assume for the purposes of this scenario that Belinda was in the course and scope of employment at the time of the injury and her workers’ compensation claim is accepted. Your options for subrogation here are murky at best. Do you try to collect from the homeowners insurance? Does Airbnb have any liability? Let’s untangle this subrogation journey. California Law of Negligence Our first stop is to see if there was negligence involved in the cause of the accident. To help determine this, let’s look at the California law of negligence. Most simply, the subrogating carrier is required to show: A duty of care (see below) was owed ✔ There was a breach of that duty ✔ The breach of that duty caused the claimant’s injuries ✔ The claimant suffered legally recognized damages ✔ Check! All of the negligence requirements are met, but by whom? Understanding Duty of Care Property owners owe guests a duty of care to maintain premises in a reasonably safe manner. Additionally, they must warn anyone who enters their property or is staying in their home of any known hazards. When a person lawfully on the premises is injured by an unsafe condition that they were not made aware of, or that the owner should have fixed, the owner could be liable for the injury. These unsafe conditions can include, but are not limited to: Slippery surfaces Defective locks Dog bites Here the property owner owed a duty of care to make sure the bathroom tiles were properly secured and not a hazard. Their breach of duty could be actual or constructive knowledge of the loose bathroom tile. If they knew about the loose tile, or should have known about it with exercise of due care, and failed to remedy it, then they breached their duty to Belinda. That loose tile caused her to fall and the fall resulted in her injuries and thus the carrier’s subrogation damages. Liability looks pretty solid on the homeowner. However, in each particular case you are going to want to make sure there aren’t any contracts that affect the liability of the parties, especially with the added complication of involvement of Airbnb. When looking at premises liability in California, consider: Who owned the property? Who possessed it? Who controlled it? Who had a duty to maintain it? The homeowner obviously answers “me!” to all those questions. Control is interesting, though, because you could make the reasonable leap in thinking that Airbnb was in control of the premises at the time of the accident. The home was part of their inventory and they do market the property and make a profit from its rental. But did Airbnb control the premises at the time of Belinda’s unfortunate accident? Airbnb’s premises liability policy Airbnb acts as an agent to secure bookings for rental properties, but is not the owner or operator of the premises and therefore does not “control” it. When guests are at the premises, they are covered under the homeowners’ insurance policy. However, to be a good partner to their hosts, Airbnb offers “Host Protection Insurance.” This is an insurance policy that is in effect whenever a host is renting their home to guests. It’s free to hosts and provides a million dollars per occurrence for injury to guests or damage to the host’s property. Airbnb has this great insurance plan, so you can just recover your subrogation claim from them? Not so fast. There are a number of scenarios for recovery: In California, homeowners don’t have to carry homeowners insurance unless the property has a mortgage. So, if there is no homeowner’s insurance policy in effect, the injury coverage would default to the Airbnb Host Protection Insurance. This is the tidiest scenario, but uncommon. If the Airbnb does have homeowners insurance, there could be varying levels of coverage from property to property. If the homeowner only has earthquake insurance, for example, the claim would again fall on Airbnb’s insurance. If the host has homeowner’s insurance that covers guests’ injuries, Airbnb’s Insurance plan stipulates that the homeowner’s insurance be tapped first and completely before it kicks in. It’s important to note, too, that Airbnb’s insurance does not cover intentional injuries or damage to the premises. How do you collect? Collecting on a case involving an Airbnb can be complicated since there are so many factors and overlapping coverage issues and scenarios involved. The first step to determining where to look for collection would be to determine the amount and type of homeowner’s insurance existed in effect during the rental period. If you’re lucky and the homeowner

What you need to know about premises liability Read More »

SMS Joined Kids’ Chance at PARMA

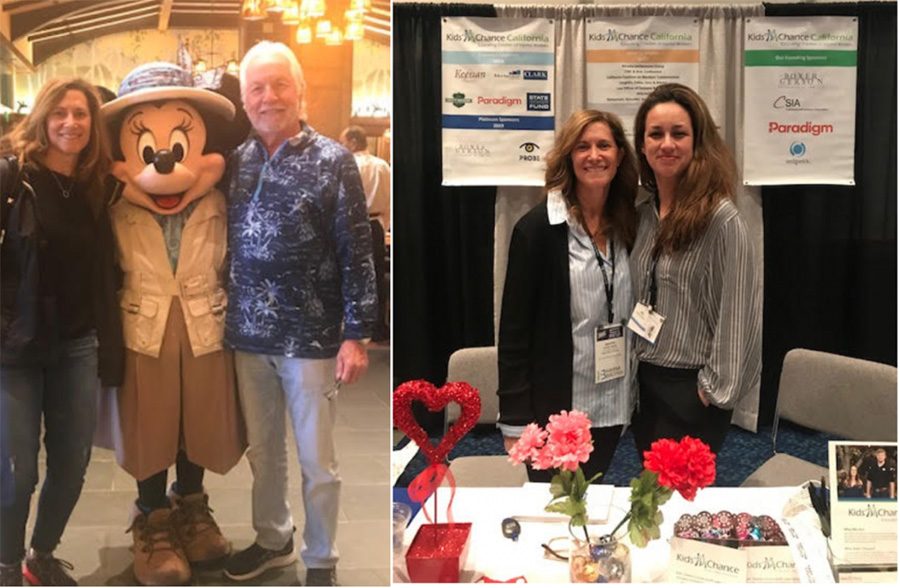
SMS Joined Kids’ Chance at PARMA (left) Jennifer McCaw, Steven Siegel & Minnie, (right) Jennifer McCaw, Kristen Chavez PARMA, the Public Agency Risk Management Association, recently held its 45th Annual Conference and Siegel, Moreno & Stettler was there in full support of Kids’ Chance of California. A Bit About PARMA The association “provides a forum for California public sector risk managers to share ideas on how to perform their duties in this emerging field.”  And what better setting for it than the happiest place on earth – the Disneyland Hotel in Anaheim, California, which is where The 2019 PARMA Conference took place on February 10-13th. Having “grown from [a] tiny band of risk managers, to an organization that spans the entire State of California,” with 600+ members from six local chapters, this gathering provides an opportunity for members to network, while sharing experiences and risk management techniques. And it’s also a place for complementary nonprofits, like Kids’ Chance, to connect with potential sponsors. Kids’ Chance Kids’ Chance of California is a non-profit organization “whose mission is to provide need-based educational scholarships to the children of California workers who have been fatally or seriously injured on the job.”  The PARMA Conference provided a great opportunity to reach out the public entity communities who really support and believe in the Kid’s Chance mission. Thank you, Steve Siegel, with Siegel, Moreno & Stettler for being the first donation at the conference.And, for my part, I was able to connect with an amazing group of fellow volunteers and supporters running the Kids’ Chance booth, which included: Edward Canavan of Sedgwick, who spoke on behalf of Kid’s Chance at the conference; Larry Costello, with Padre Dam, a PARMA board member who supported Kids’ Chance immensely at the conference; and, Kristen Chavez, CEO of Work Comp Central who is always ready to offer her time and resources to help Kids’ Chance. Overall, the conference was a success for PARMA participants and for Kids’ Chance – a win-win all around! What’s Next? We look forward to continuing our work with Kids’ Chance at future events which will be the CIA conference April 8-9. Siegel, Moreno & Stettler’s will also be attending PARMA’s next event – the upcoming San Diego/Imperial Valley Chapter Liability Half-day. The event takes place on March 27th and will include a presentation by two members from our Subrogation Litigation Team, SMS attorneys Kelsey Daniel and Chalsie Keller. Their training will focus on How to Win at The Subrogation Game. Be sure to click through to learn more and to register to attend! Search for: Search Categories COVID-19 Depositions Firm Announcements Firm Notifications Giving Back Law New Attorneys New Location Property Subrogation Subrogation Workers' Compenstation Archives Archives Select Month August 2026 March 2026 January 2026 July 2025 May 2025 March 2025 January 2025 November 2024 October 2024 July 2024 June 2024 January 2024 December 2023 November 2023 August 2023 May 2023 April 2023 March 2023 February 2023 May 2022 March 2022 February 2022 January 2022 November 2021 October 2020 September 2020 August 2020 June 2020 May 2020 April 2020 March 2020 January 2020 November 2019 October 2019 September 2019 March 2019 February 2019 January 2019 August 2017 January 202 Subscribe To Our Blog First Name Last Name Email * Edit Template

SMS Joined Kids’ Chance at PARMA Read More »

Increasing the Odds: Strategies for Mediation as a Workers’ Compensation Subrogator

Increasing the Odds: Strategies for Mediation as a Workers’ Compensation Subrogator Mediation as a subrogator is like playing a two-player game as a third player. The game is designed for two players, and those two players don’t understand how you fit into their game and they don’t really want you there. Your pieces to the game, however, hold a lot of power if you place yourself in the right position for mediation. BY CHALSIE KELLER AND KELSEY DANIEL As a subrogator, you will likely be ignored for a good portion of the mediation. This is because the mediator tends to focus on the Injured Worker and Defendants as the parties to the case, thinking they are the most important players to the mediation. The mediator usually has a plan to come to you at the end of the negotiation with the singular goal of reducing your recovery as much as possible to get a settlement within the bounds of the “deal” they have already worked on with the Injured Worker and Defendants. Even worse in some cases, the mediator may view you as another source of money to contribute to the overall settlement. The solution to controlling the outcome of the game, is to place yourself in the best position to negotiate with all parties. This usually translates to “leave your options open” and “get creative.” DIFFERENT TYPES OF SETTLEMENT Subrogation is a unique situation in the civil arena because the goal may not always be to get as much money from the settlement possible. Sound crazy? The other parties to the case may think so too. Approaching mediation from this perspective can give you great leverage to getting the best overall recovery for the claim. A settlement where the Subrogator takes less direct money in reimbursement does not translate to an overall lower recovery. Although it seems contradictory, the opposite is often true. A settlement where the Subrogator agrees to recover less direct money from the overall settlement in exchange for a stipulation to credit, or a third party compromise and release, can be a much better bargain than receiving a larger amount of direct money from the settlement. When the underlying claim is left open, the carrier faces high exposure that an even exceed the estimates at the time of settlement. Closing off a “bleeding” claim can be much more beneficial than cash in hand. To use this leverage to your best advantage, knowledge of the status of the workers’ compensation claim, and the different settlement options available to you based on that status, are key. Different states have different rules governing each of these options, but most allow a carrier to obtain some sort of credit that makes all of these strategies options for the Subrogator. There are three major types of settlement options: Direct Cash Only; Direct Cash with Claim Credit/Closure, and; Claim Credit/Closure Only Let’s use the following example to better understand each option and how they would play out in this scenario: The worker’s compensation claim total estimated cost is $90,000. $70,000 in benefits have been paid to date. $20,000 in benefits are in reserves for the permanent disability rating and future medical care Identified by the Panel Qualified Medical Evaluator. The civil subrogation team has discovered the third party civil defendants have a $100,000 policy available to recover from in the subrogation case. Both the injured worker and the Subrogator have filed suits and made a claim for the $100,000 policy. Direct Cash Only Direct Cash Only settlement simply means your subrogation recovery value only comes from whatever money you are able to recover from the third party subrogation case. This kind of settlement agreement generally arises when there is insufficient insurance available to recover from the Defendant. When this occurs, you have three people fighting for the same money (the Subrogator, the Injured Worker and the Injured Worker’s Plaintiff Attorney). In our scenario, the Defendant’s policy limits were $100,000. If the defendant’s offer their full policy for settlement, each party (the Subrogator, the Injured Worker and the Injured Worker’s Plaintiff Attorney) could equally splitch the $100,000 giving them cach $33.333.33. Your recovery from this scenario is the value of the direct cash you are settling for, $33,333,33. You can choose this option for settlement with both an open or closed Workers’ compensation claim. However, if your claim is closed, your recovery ends there. Insufficient funds from a Defendant, usually due to low policy limits, is a prime example of why it is so important to communicate with the Subro Team (claims representative, subrogation representative, subrogation attorney) to keep the underlying workers compensation claim open. If the claim is open, you can petition your State’s appeals board for credit for the net recovery of the injured worker (jurisdiction permitting) and recover an additional $33,333.33 in claim credit. This credit is required to be spent on the claim, with itemized proof by the injured worker, before the carrier is obligated to pay our benefits under the claim. This effectually closes the claim in many scenarios. If you have an agreeable injured worker and Plaintiff attorney, you can choose the next option for settlement, Direct Cash with Claim Credit Closure. Common Fund Doctrine and Interpleader As an additional element of concern with low policy limit cases, and in states where the Subrogator has a first right of recovery, the Subrogator’s damages alone will often exceed the policy limits, or will at least exceed what the plaintiff attorney thinks you are entitled to recover. An argument that will likely be made is that the Plaintiff attorney put forth more effort and therefore procured the settlement. This contention, when applicable in your jurisdiction, is commonly referred to as the Common Fund Doctrine. The doctrine stands for the premise that where one creates a fund to which others have a claim, that one is entitled to first recover their costs of litigation and attorney’s fees. It is an equitable principal designed to prevent unjust enrichment. Some states

Increasing the Odds: Strategies for Mediation as a Workers’ Compensation Subrogator Read More »

Finding Fault. Successfully Identifying Workers’ Compensation Recovery Opportunities

Finding Fault. Successfully Identifying Workers’ Compensation Recovery Opportunities “Impossible under magnifying glass” by wuestenigel is licensed under CC BY 2.0. To view a copy of this license, visit: https://creativecommons.org/licenses/by/2.0 A day in the life of a workers’ compensation claims professional can be hectic to say the least. New losses that demand immediate attention come in continually. But subrogation does not have to be a thorn in the claims professional’s side. Familiarity with basic workers’ compensation subrogation fact patterns and the steps to take once they have been identified can ease this task. Let’s explore some of the usual suspects. Subrogation Recovery Potential Each claim brings in calls and correspondences from applicant attorneys, doctors, employers, case managers, investigators, defense attorneys, lien claimants, and injured workers. With every request for treatment and report that comes in, there are rules and hidden deadlines around every corner. Supervisors require diary reviews, updates, and plans of action, and clients seek account audits. On top of all that, the claims professional also is responsible for identifying subrogation recovery potential for each claim. Fact Patterns In general, subrogation in the context of a workers’ compensation case comes in several distinct fact patterns. Motor Vehicle Accidents. The easiest of all fact patterns to identify with subrogation potential is a motor vehicle accident. When a report comes in that mentions an injury that was caused by a car accident, subrogation should be pursued to determine who was at fault for the accident. Securing a copy of the police report is key for this purpose. Once the report is received, the responsible driver and owner should be put on notice of the carrier’s intent to pursue subrogation. A demand must be made for the insured to open a claim with his auto insurance carrier. A request should be made to the employer and employee for any photographs of the vehicles involved, documentation of any repairs made to the vehicles involved, and a statement made by anyone involved in the accident or who witnessed it. Construction Site Accidents Accidents on construction sites come in all shapes and sizes. Early identification of subrogation potential involving a construction site accident is paramount because the scene of the accident and instrumentation involved often can change quickly. Even a short delay of a week or so in getting a subrogation inquiry up and running can prejudice the chances of recovery. Thus, when an injury comes in and the employer identifies the accident locale as a construction site, an immediate subrogation review needs to be done. Some of the more common fact patterns with subrogation potential include injuries involving heavy machinery, scaffolding, falls from heights, materials falling and striking workers, and failures to guard against dangerous conditions. Once subrogation potential is identified, requests should be made for witness statements, Occupational Safety and Health Administration (OSHA) reports, contractor reports, photographs of the scene, rental agreements, and job site contracts. Premises Liability Of all the subrogation fact patterns, these types of cases are the most often overlooked by claims professionals and insured employers alike. Subrogation potential in slip, trip, and fall scenarios often is discounted quickly on the assumption that it was nothing more than an accident caused by the injured worker not paying attention. While contributory fault of the injured worker is a consideration in all premises liability cases, it does not mean that there is no subrogation potential. Any time an injury involves a slip, trip, fall, or some other accident caused by an encounter with a condition present on the property, the claims professional should take a moment to step back and consider whether a third party was involved in creating the condition that led to the injury. Once identified, photographs of the condition responsible for the injury immediately should be secured. Products Liability These cases have the most obvious fact patterns but can be the most expensive and problematic to pursue. When an injury occurs due to an encounter with a machine, tool, or piece of equipment, subrogation should be considered. Discussions with the employer and employee should focus on whether a defect or failure of the equipment contributed to the accident. Ofentimes these fact situations involve contributory fault of the injured worker and employer surrounding misuse of equipment or failure to train. Nonetheless, if the scope of the injury is large, at least a basic analysis of product design or manufacturer defects should be completed. Securing a copy of the OSHA report often can assist in the fact gathering and analysis of the issues involved. In very serious cases, an expert can be consulted early on to inspect the product. Ultimately, these cases hinge on the testimony and opinion of an expert concerning the product. Miscellaneous Patterns Not all subrogation fact patterns fit neatly into a category. Any time an accident occurs and you find yourself asking, “How did that happen?” it’s probably a good indication that there may be subrogation potential. Follow that intuition by asking questions of the employer and employee to determine whether a third party potentially could be involved in the cause of the injury. If there is ever a doubt, it is better to be safe than sorry. Our attorneys can help you sort out the right questions to ask and evidence to preserve to ensure subrogation opportunities are not missed. Sometimes a phone call is all it takes. Have a question? Reach out! A version of this article originally appeared in Subrogator Magazine. Search for: Search Archives Archives Select Month January 2019 August 2017 Subscribe To Our Blog First Name Last Name Email * Edit Template

Finding Fault. Successfully Identifying Workers’ Compensation Recovery Opportunities Read More »

SMS to Open in Sacramento

SMS to Open in Sacramento To better serve our Northern California clients, Siegel, Moreno & Stettler is pleased to announce the opening of our newest location in Sacramento. SMS now has six locations throughout California to to help us be more agile and flexible in our Worker’s Compensation Defense and Subrogation practice throughout the state. Our new location is: 3841 N. Freeway Blvd, Suite 130, Sacramento, CA  95834 Search for: Search Archives Archives Select MonthAugust 2017 Subscribe To Our Blog First Name Last Name Email * Edit Template

SMS to Open in Sacramento Read More »